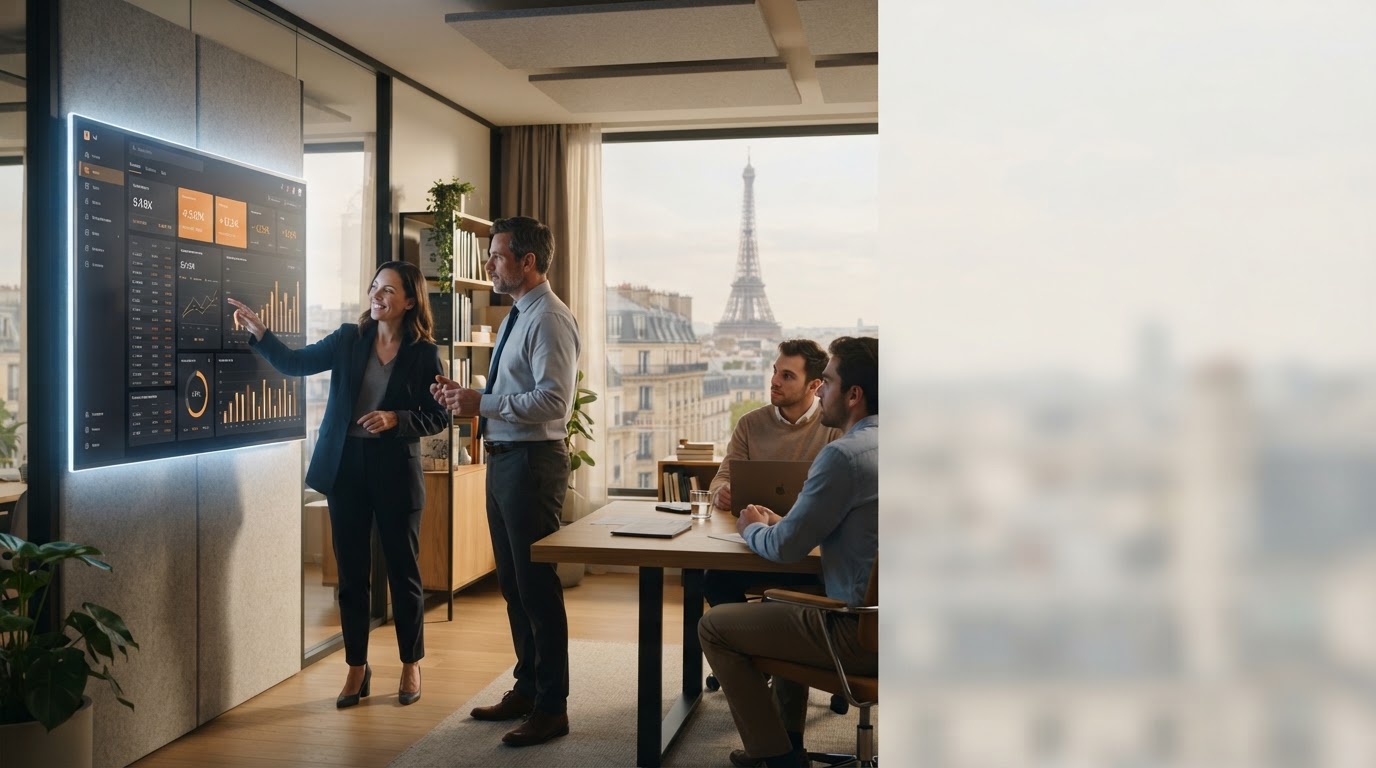
Sitedoro continuously monitors more than 500 trading pairs — crypto-assets, currencies, indices and commodities — and filters statistical noise to only return signals relevant to decision-making.
Illustrative overview of the interface — the values displayed do not constitute actual market data.
Sitedoro's engine ingests high-frequency market feeds and restructures them into readable indicators, with no perceptible lag for the end user.
Each module responds to a distinct stage of the decision cycle, from anticipation of market movement to control of the risk taken.
The models identify recurring patterns in historical price and volume, then estimate the likelihood of multiple near-term scenarios. The results are presented with their margin of uncertainty, without categorical statements.
Each signal is accompanied by a calculation of potential exposure, based on the recent volatility of the asset. The objective is to size a position consistent with a risk tolerance defined by the user.
Custom thresholds trigger a notification when a change in trend, volatility or correlation exceeds a defined level, to avoid constantly monitoring screens.
The mathematical rigor of the processing and the transparency of the path are at the heart of the design of Sitedoro. No step is presented as an opaque black box.
Price, volume and order book feeds are collected continuously from multiple market sources, time-stamped and normalized into a single format before processing.
Statistical and machine learning models clean up anomalies, weight correlations between assets, and isolate meaningful variations from ordinary market noise.
The result is converted into a readable recommendation — likely direction, confidence level and risk exposure — delivered to the user in the form of an alert or dashboard.
Sitedoro was designed for users who wish to keep control of their decisions while relying on data processing that a human cannot reproduce on the same scale. The platform does not replace user judgment; it reduces the time needed to inform them.
The technical team documents each indicator displayed so that its calculation method remains consultable, with the aim of transparency towards demanding financial users.
The platform adapts to the decision-making pace of each investor profile, from intraday trading to medium-term portfolio management.
How Sitedoro identifies trend reversals before market consensus: by crossing volume, momentum and inter-asset correlations over windows of a few minutes, the engine signals structural breaks before they are visible on a traditional chart.
Analysts use real-time correlation maps to adjust an existing hedge when two asset classes begin to move in unusual ways relative to each other.
An aggregated sentiment indicator, calculated from the behavior of order flows, helps distinguish a fundamental movement from a short-term reaction before strengthening or reducing a position.
The average latency observed under normal market conditions is less than 200 ms between the reception of a price feed and the updating of the corresponding indicator. It can increase slightly during peaks of extreme volatility, when the volume of messages per second exceeds the absorption capacity of the data sources themselves.
Communications between the interface and the servers are encrypted in transit. Brokerage API connection credentials, when provided by the user, are stored separately from analytical data and are never used to execute orders without explicit user action.
Programmatic access is offered for accounts requiring integration with an internal trading tool or portfolio management system. The technical documentation details the request limits and available response formats.
Market volatility does not stop outside of business hours. Implement continuous monitoring before the next phase of significant movement.